Engineering, integration, AI.
Field-tested integration work.
Peer-reviewed work in IEEE + Springer.
The builure Pulse, hosted by Inshu.
Workshops, panels, and roundtables.
Who we are and how we work.
Talk to the team in Melbourne.
Investor enquiries and materials.
Security, compliance, and certifications.
Blogs · Issue 20 · 2026
Written by the team that ships it: broker workflows, MuleSoft patterns, compliance posture, and what actually held up in production.
Revolut’s new ADI licence marks a significant shift in Australian banking competition. While it does not currently offer home loans, mortgage brokers should understand what its growing customer base,and future lending ambitions could mean for the broker channel.
By Inshu Misra
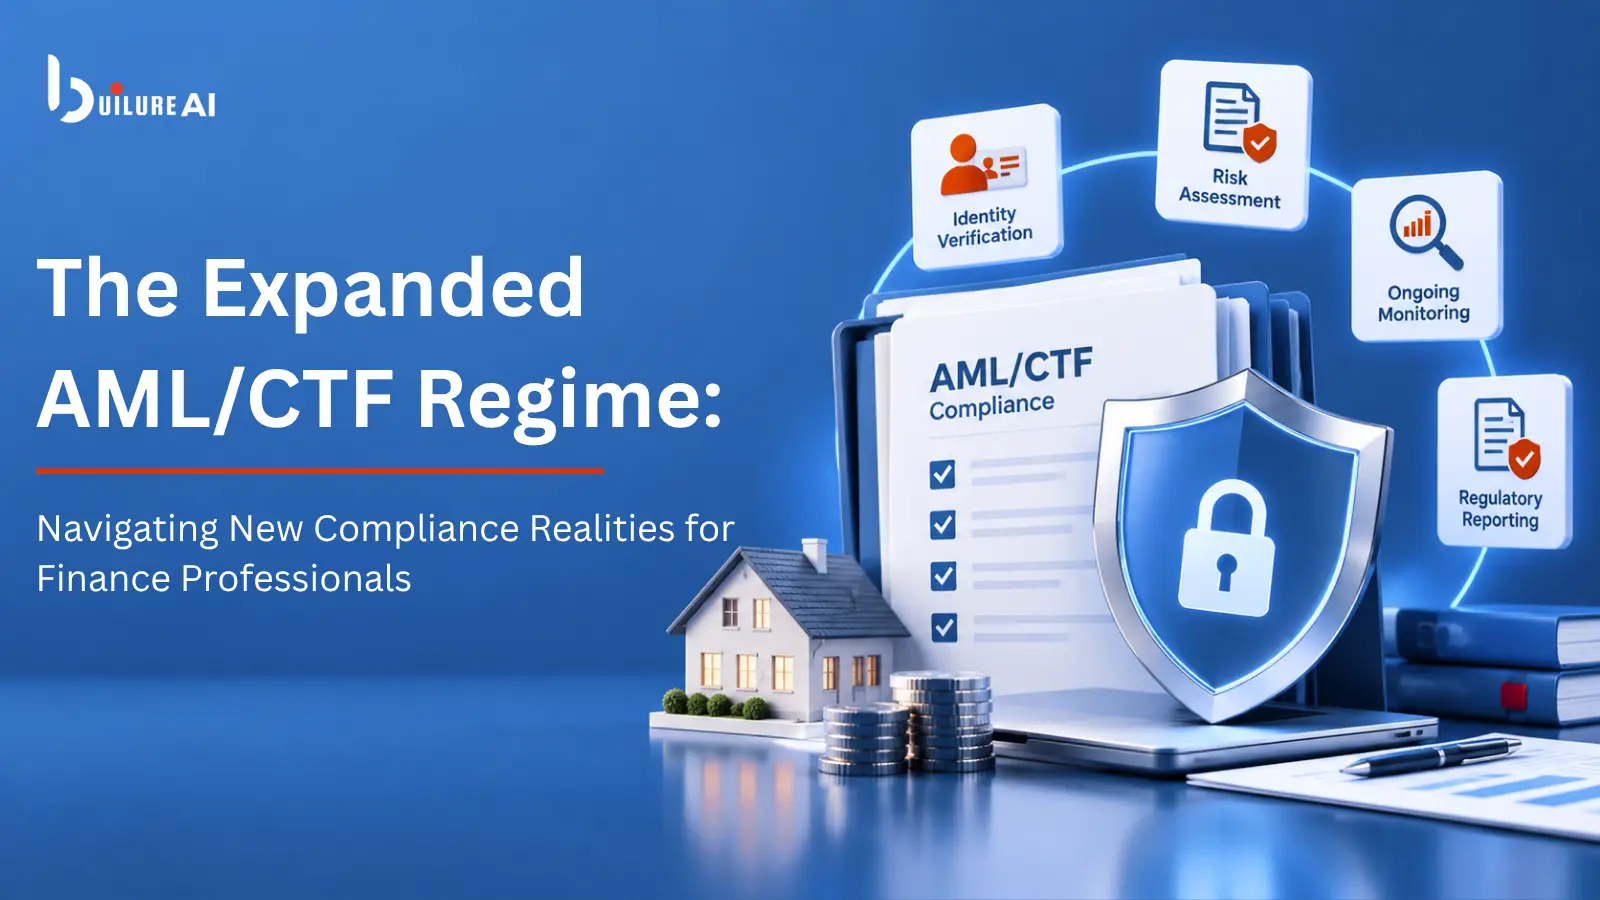
Australia’s expanded AML/CTF regime introduces new compliance obligations for professional services and raises important questions for commercial finance brokers. Here’s what mortgage brokers need to know about the changes, audit trails and evolving compliance expectations.
Your CRM manages the pipeline, but your intake workflow sets the foundation. Discover how digital fact finds, ID verification and automated compliance workflows can help Australian mortgage brokers reduce manual work and improve file consistency.
Explore how Australian mortgage professionals can navigate independent lender rate cuts, cooling loan commitments, and a structural housing shortfall to grow volume in 2026.
Discover how leading Australian mortgage brokers are using AI in 2026 to streamline lender policy research, automate compliance, capture leads 24/7, and scale operations without burning out.
Discover what the latest RBA cash rate decisions mean for your brokerage. Learn how to track borrowing capacity, lender rate pass-throughs, and client trigger points to turn market uncertainty into new business.
As Australian lenders rapidly update their credit criteria in response to APRA caps and trust restrictions, mortgage brokers must pivot quickly. This practical playbook outlines the five biggest policy changes impacting borrowing capacity.
APRA has introduced historic debt-to-income (DTI) lending limits and a new three-tier banking framework. Discover how these structural changes impact borrowing capacity and how smart mortgage brokers can turn these regulations into a competitive advantage.
Serviceability assessments, APRA's February 2026 DTI cap, and three consecutive RBA rate hikes are reshaping what borrowers can access in 2026. Here is what mortgage brokers need to monitor right now.
The 2026-27 Federal Budget is reshaping the Australian mortgage landscape. Here is how smart broker firms are building resilience and growing their business right now.
The complete archive
Every builure article, going back to the start.